Selling your house to pay for assisted living


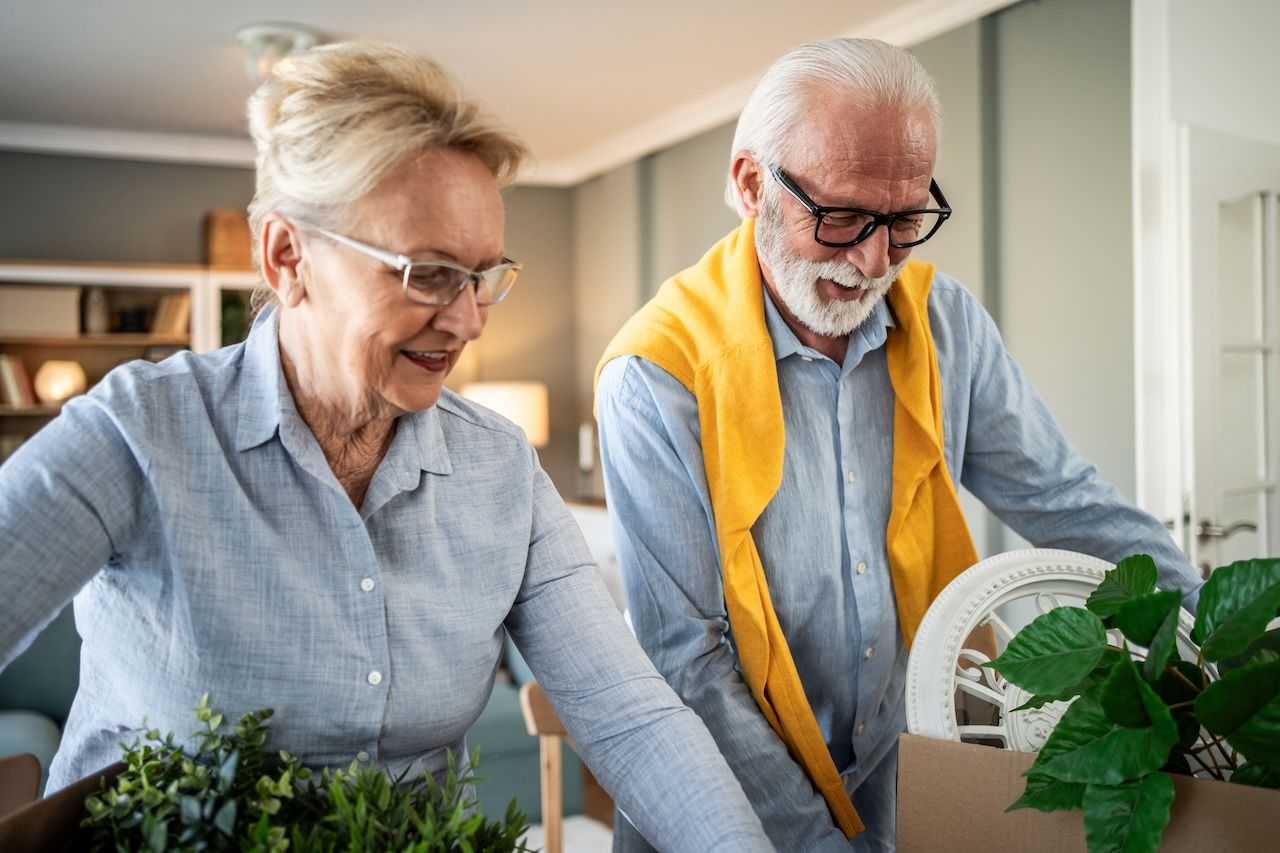
Selling your house can help pay for assisted living, but the right choice depends on your finances, local housing market, care costs, and personal priorities.
Selling before a move provides funds upfront, while selling afterward may make the home easier to stage but can create overlapping expenses.
Savings, long-term care insurance, benefits, family support, bridge loans, and reverse mortgages may also help cover assisted living costs.
If you or someone you love may need assisted living, selling a home can be one way to help cover the cost, but it is not the right choice for everyone. Health or mobility changes can make it harder to stay safe and comfortable in a well-loved home. An assisted living community may offer the added care, comfort, connection, and support needed for this next chapter.
The financial side of this move can be complicated. A home may also hold a lifetime of memories, making the idea of selling especially difficult. If you’re already discussing this option, you may have heard a firm, "I'm not selling my house."
That’s why it helps to review every available way to pay for assisted living with your loved one. Family members, friends, and others in the care circle can help explore the options. A thoughtful conversation about the costs, benefits, and tradeoffs can make the transition feel more manageable.
What is assisted living, and might you need it?
Assisted living, a form of long-term care, combines residential living with access to 24-hour personal care. Although it doesn’t provide medical care, it may offer laundry and housekeeping services, social activities, health and wellness programs, medication assistance, and meal plans.
Assisted living may be the next step for an older adult who is no longer safe or comfortable living independently but doesn’t need skilled nursing care. It can fill the space between fully independent living and a setting that provides a higher level of care.
The Department of Health and Human Services estimates that 69% of Americans will need some type of long-term care during their lives.1
Does assisted living help with activities of daily living?
Assisted living options range from individual carriage homes and luxury condominiums to apartments of various sizes. The range of housing styles can be broad, but the services are often more important. When comparing communities, you’ll likely want to know which kinds of support each one offers. A common feature is help with activities of daily living (ADLs). This may include support with personal hygiene, toileting, dressing, grooming, eating, mobility, and transportation. These are routine activities that someone may need to complete safely each day.
Assisted living can provide needed support while helping an older adult preserve their independence. It may also offer continued social interaction, fewer household chores, and access to professional assistance 24 hours a day. This balance of privacy and support may suit someone who can no longer manage ADLs without help.
How much does assisted living cost?
According to the National Center for Assisted Living (NCAL), there are almost 29,000 assisted living communities in the United States. They range from communities offering essential services to luxury accommodations with private resort amenities. With so many types available, prices and included services can vary considerably. Every level of assisted living provides professional care, comfort, security, and safer living conditions.
More expensive communities may provide a wider range of services, activities, fine dining, personalized concierge services, swimming pools, and gyms. When comparing costs, consider which amenities are included in the monthly price and which cost extra.
Paying for assisted living is a real concern for many older adults and their families. Although it can be expensive, the all-inclusive structure of many communities may mean fewer separate monthly bills for residents. According to our Cost of Care survey, the median price paid for assisted living in the United States in 2021 was approximately $4,500 per month. Having several family members contribute may make the cost easier to manage, although everyone should understand how much they can reasonably provide.
Costs vary by location and amenities
Depending on the location, level of care, and amenities you choose, assisted living may cost from $2,000 to $8,000 per month or more. Some communities charge a flat monthly rate. Others add fees for specific levels of care, services, and activities, so it’s important to understand what the stated price includes.
Communities near large cities may cost considerably more than those in rural areas. Average local income and the availability of assisted living can also affect prices. The same type of apartment or support may therefore carry a different price depending on where you live.
Should you sell your house to pay for assisted living?
If you own a home, you may wonder whether selling it is the best way to pay for assisted living. The answer depends on factors such as the property’s value, how long the proceeds may last, property taxes, the amount of money you need, and the stability of your local housing market. Looking at these details together can show how much support a sale may provide.
You’ll also need to consider possible tax consequences and the fact that selling means giving up an asset you might otherwise leave to your heirs. These considerations may be as important as the immediate need to pay for care.
Selling your house before moving to assisted living
Selling your house before you move gives you access to the proceeds upfront. Those funds may help cover monthly assisted living costs, moving expenses, past utility bills, and other transition costs. Having the money available before the move may make these expenses easier to manage.
There are also drawbacks to selling before you relocate. Showing a house while you’re living in it can be inconvenient, especially when potential buyers want to visit at difficult times. You’ll need to keep the home neat and ready to show. An occupied house may also not present as well as an empty, staged home.
Selling your house after moving to assisted living
Waiting to sell until after you move into assisted living also has advantages. When you’re no longer living there, it may be easier to clean, arrange, and stage the house for the best possible presentation to potential buyers.
You’ll also be settled in your new home and won’t need to manage visitors walking through the house while it’s listed. This can remove one disruption during an already significant transition.
However, if the house doesn’t sell quickly, you’ll face overlapping expenses. You’ll need to keep the utilities on, continue making mortgage payments, and pay the costs associated with your new living arrangement at the same time.
Before delaying the sale, consider your home equity, new living costs, and the ongoing expense of maintaining your former home. Compare those costs with the possible benefits of waiting. A bridge loan may temporarily provide funds until the house sells.
Other ways to pay for assisted living
Selling your home isn’t the only way to pay for assisted living. A real estate agent may be able to help you consider options involving your property and the timing of a sale. Some of the most common payment methods are outlined below like long-term care insurance or a reverse mortgage. Each has limitations to discuss with your loved ones and a financial planner.
How a senior bridge loan works
A bridge loan provides temporary funds to older adults who are selling their homes but need money now for moving and living expenses. It covers the gap until your home sells, when the loan must be repaid in full. These loans typically have high interest rates and usually require collateral, such as your house, a family member’s house, real estate, or other assets. In general, bridge loan terms are similar to a line of credit.
Senior bridge loans have some advantages. Until the principal is due, several people may divide the monthly payments. If family members or other loved ones can help, you may split the costs until the home sells and the loan is repaid. Approval typically takes only a few days, which may help if you or your loved one needs to move into assisted living on short notice.
How a reverse mortgage works
Selling your home is one way to access cash, but a reverse mortgage may be an alternative if you don’t want to sell immediately. A reverse mortgage remains in place for a longer term than a bridge loan.
A reverse mortgage is a loan for older homeowners that provides access to their home equity. Instead of paying the lender each month, the bank, insurance company, or loan holder pays the homeowner a monthly amount based on the property’s fair market value at the time of a home sale.
However, the owner must remain in the house. This option may work best for a couple when only one person needs to move into assisted living or nursing care and the other remains home. The homeowner remains responsible for insurance, property taxes, and other expenses.
The loan must be repaid when the homeowner moves out, dies, or sells the house. If you have a reverse mortgage, you won’t be able to leave the home to your heirs unless another source of income is available to repay the mortgage. This possible effect on inheritance is an important consideration.
Before moving to assisted living, talk through your payment options with loved ones, a trusted friend, or a financial advisor. Reviewing the alternatives together can help you consider both immediate care expenses and longer-term financial needs.
You might start the conversation with, "I'm considering selling my house," rather than saying you’ve already decided. This leaves room for your loved ones to ask questions and discuss other possibilities. Stay open to alternatives so you can determine whether selling fits your financial circumstances, priorities, and care needs.
Should you sell your house?
Deciding whether to sell your house to pay for assisted living is deeply personal and requires careful consideration. Although a sale can provide money to cover care, it also carries significant emotional and practical consequences that only the homeowner can fully weigh. The home’s value is only one part of the decision.
There’s no single answer that works for every person or family. Your circumstances, financial position, and personal priorities are unique. Gather information, consider the short-term and long-term financial effects, and talk through the choices. Then choose the path that supports financial stability and personal well-being.
Whatever you decide, approach the conversation and decision-making process with compassion, care, and thoughtfulness. The goal is to choose an option that supports appropriate care for you or your loved one while respecting the homeowner’s wishes and financial circumstances.
unding solutions to help you age in place
Make a plan today for future care needs with funding solutions that fit your budget.
Expert reviewed by

Eric Schwarz, CFP®, CTFA, CEPA
Eric W. Schwarz reviews financial content related to the aging experience. A Certified Financial Advisor and Certified Exit Planning Advisor with over 30 years of experience counseling families on financial management, Eric brings a wealth of knowledge in the fields of...
Written by
Arthur Bretschneider, MBA
Arthur Bretschneider is Chief Product Officer at CareScout. As a third generation leader in the senior living industry, Arthur brings both deep compassion and a wealth of practical experience to his work at Seniorly. Arthur holds an M...